Today my paycheck included a huge reimbursement.
Tonight I paid off the credit card that's been carrying a balance since June (payments and charges since then).
I also paid the first bill in full for the new JetBlue American Express card that I got. (I wonder where I'll take my free trip next year?!)
I even have some money left over. (Of course, it will go toward expenses at the end of the month.)
It may be another month before I fully feel the relief to be in balance again. (Maybe I will find a few dollars for my long-neglected Roth IRA?)
Phew. (Whew.)
Showing posts with label budget. Show all posts
Showing posts with label budget. Show all posts
Tuesday, November 15, 2011
Sunday, November 07, 2010
Cashola
So how about that budget project? I continued the cash-only goal for October (with a few exceptions) and kept track of my spending.
Groceries: This month I only spent $87, down from $100. I think I bought fewer ingredients. However, this also includes some food bought for a potluck-type get-together. So this means I used my money better, ate more of what was already in the cupboards, and/or ate less. Most likely a combination of all three.
Restaurants: $25, which is roughly the same as last month, except it was spread out over more smaller pieces. The biggest one was a dinner out with some flickr friends.
Shopping: $65 for household goods, plus another $46 for some clothes at Target [an entire outfit--a pencil skirt, a thin sweater, and earrings/necklace. One of our outings last month was a talk by Clinton Kelly, so I was definitely inspired to get some clothes that are polished and mature, and also have color, texture, pattern, or shine (hence the coordinating jewelry--a nice purple to contrast the jewel-toned dark green). I haven't worn the outfit yet but look forward to breaking it out and feeling very put-together.]. Total of $111, which sounds like a frightening number.
Transportation: increased to $60 in October, because I have been commuting to an office four or five days a week.
Total spent for the month: $305, down from $353 in September. Not too shabby, especially considering that my credit cards have been nice and low, which means that I can spend more of what little money I have on regular things.
Sunday, October 03, 2010
Budget: The Breakdown
September is over and so is my first month's budget experiment. How did it go?
--I spent $99 on groceries. I originally budgeted $80 a month for regular groceries, since I don't eat much and I don't eat anything expensive. There's a produce shop around the corner that I have been visiting for fresh things to cook with. But I think the cooking has led to more money spent, on ingredients to make things instead of buying more simple things.
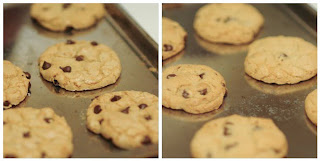 But look! My third try making cookies finally resulted in yumminess!
--At Costco I spent a mere $68. I used a debit card for that (at the end of the month).
--I spent too much on "fun" stuff out with friends: a total of $52 on a restaurant, bowling, a potluck dinner, a cab share, a snack for book club.
--Temping around the city, I needed to get around and thus spent $40 on metro cards. (For one week and a half, I am proud to exclaim that I spent zero dollars on transportation, because I biked to a temp job! A savings of $31.50!! Plus free exercise and fresh air! Win-win situation for sure. This means that metro card money will stretch into next month a little.)
--$10: I bought a swimcap to use the pool at our new gym (right now the husband is covering my share of the fees. Once I have a little more income I will pay for part of it.)
--I had to buy a read-aloud book for my class, and I couldn't help treating myself to a new MadLibs (it was on clearance!)(We hope to have some people over soon and that can make for some extra fun downtime!). That was $15 at the bookstore.
This past weekend we went to Target. I made myself a list of a few essentials that I needed, and I was able to stick to that list. But I also bought a blanket for $20. (We have a new bed and need more bedding for the colder weather. The husband bought a comforter too.) So the trip, including parking, cost me $55. Yikes.
(At one point I took out another $20 in cash because I thought I would need it for an outing, but then I decided not to go. That money still got spent, though.)
Grand total for the month: $340.
....
Overall, I did a fair job. At the beginning of the month I was a little more cavalier with money, spending more out with friends. That's the biggest spending piece that was "unnecessary." So in the future I need to find a way to reconcile fun with my very limited budget. I'm not looking forward to that. I hope that a few friends will understand and I can still have a good time. :)
Transportation was a huge cost and my budget didn't take that into account. I was still in summer mode or paycheck mode. The $25 I budgeted was for gas, which is actually very generous since I rarely drive and so only fill up every other month or so. All this year I got monthly metrocards at work pre-tax. Of course now I buy pay-per-ride metrocards out of pocket. I don't know why I forgot to take that into consideration. Next month's transportation budget will have to be $50 at least.
Groceries, like I said, was only okay. I didn't buy impulse fun food things, but that baking stuff meant that I bought three pounds of butter over the course of a couple weeks, at four dollars each. That's twelve dollars that seems a little extraneous. If I were smart and motivated, planning out meals and ingredients would be a good idea. I need to think harder about using what we already have, too, instead of always buying more. Like the frozen strawberries for smoothies. I like buying fresh ingredients at the produce shop, and so far it seems pretty cheap too (I bought two jalapeno peppers for our second salsa attempt--they cost eighteen cents!) in addition to being smart economically and environmentally.
Target and the bookstore were pretty much necessities, and unfortunately that kind of spending won't go away. I will try to spread out what I need over more time though, if that's possible.
....
Now for the emotional report...
On the one hand, it's been easy not to spend money on more things. I could easily have spent a lot more on going-out food/drinks/activities. I shouldn't have spent all that I did, but I did have a good time with friends. But in forgoing clothing, or more things at Target, I found myself thinking, "Oh, I'll just buy that next time." Which is dangerous and completely misses the point of the whole challenge by making it a temporary lark. I will probably not have any more money next time than I do right now! Oh god, this is so depressing.
BUT. It's a good learning tool in that it's easy to say no, to cut back, to ride a bike if it's nearby and the weather is good. Now that the weather has turned chilly, the bike will not be a viable option for much longer. With the looming holiday season, I'm already planning out homemade/handmade gifts.
Overall, I will have to revise my budget a little bit to make it more realistic, and I will also have to adjust a few ideas and habits. I don't think this is something I can keep up long term, but I think I'll do it again for October. I do like how using cash keeps me honest, and keeping track of every single thing keeps me thinking about what I'm spending. I can Just Say No!
...most of the time. :)
--I spent $99 on groceries. I originally budgeted $80 a month for regular groceries, since I don't eat much and I don't eat anything expensive. There's a produce shop around the corner that I have been visiting for fresh things to cook with. But I think the cooking has led to more money spent, on ingredients to make things instead of buying more simple things.
 But look! My third try making cookies finally resulted in yumminess!
--At Costco I spent a mere $68. I used a debit card for that (at the end of the month).
--I spent too much on "fun" stuff out with friends: a total of $52 on a restaurant, bowling, a potluck dinner, a cab share, a snack for book club.
--Temping around the city, I needed to get around and thus spent $40 on metro cards. (For one week and a half, I am proud to exclaim that I spent zero dollars on transportation, because I biked to a temp job! A savings of $31.50!! Plus free exercise and fresh air! Win-win situation for sure. This means that metro card money will stretch into next month a little.)
--$10: I bought a swimcap to use the pool at our new gym (right now the husband is covering my share of the fees. Once I have a little more income I will pay for part of it.)
--I had to buy a read-aloud book for my class, and I couldn't help treating myself to a new MadLibs (it was on clearance!)(We hope to have some people over soon and that can make for some extra fun downtime!). That was $15 at the bookstore.
This past weekend we went to Target. I made myself a list of a few essentials that I needed, and I was able to stick to that list. But I also bought a blanket for $20. (We have a new bed and need more bedding for the colder weather. The husband bought a comforter too.) So the trip, including parking, cost me $55. Yikes.
(At one point I took out another $20 in cash because I thought I would need it for an outing, but then I decided not to go. That money still got spent, though.)
Grand total for the month: $340.
....
Overall, I did a fair job. At the beginning of the month I was a little more cavalier with money, spending more out with friends. That's the biggest spending piece that was "unnecessary." So in the future I need to find a way to reconcile fun with my very limited budget. I'm not looking forward to that. I hope that a few friends will understand and I can still have a good time. :)
Transportation was a huge cost and my budget didn't take that into account. I was still in summer mode or paycheck mode. The $25 I budgeted was for gas, which is actually very generous since I rarely drive and so only fill up every other month or so. All this year I got monthly metrocards at work pre-tax. Of course now I buy pay-per-ride metrocards out of pocket. I don't know why I forgot to take that into consideration. Next month's transportation budget will have to be $50 at least.
Groceries, like I said, was only okay. I didn't buy impulse fun food things, but that baking stuff meant that I bought three pounds of butter over the course of a couple weeks, at four dollars each. That's twelve dollars that seems a little extraneous. If I were smart and motivated, planning out meals and ingredients would be a good idea. I need to think harder about using what we already have, too, instead of always buying more. Like the frozen strawberries for smoothies. I like buying fresh ingredients at the produce shop, and so far it seems pretty cheap too (I bought two jalapeno peppers for our second salsa attempt--they cost eighteen cents!) in addition to being smart economically and environmentally.
Target and the bookstore were pretty much necessities, and unfortunately that kind of spending won't go away. I will try to spread out what I need over more time though, if that's possible.
....
Now for the emotional report...
On the one hand, it's been easy not to spend money on more things. I could easily have spent a lot more on going-out food/drinks/activities. I shouldn't have spent all that I did, but I did have a good time with friends. But in forgoing clothing, or more things at Target, I found myself thinking, "Oh, I'll just buy that next time." Which is dangerous and completely misses the point of the whole challenge by making it a temporary lark. I will probably not have any more money next time than I do right now! Oh god, this is so depressing.
BUT. It's a good learning tool in that it's easy to say no, to cut back, to ride a bike if it's nearby and the weather is good. Now that the weather has turned chilly, the bike will not be a viable option for much longer. With the looming holiday season, I'm already planning out homemade/handmade gifts.
Overall, I will have to revise my budget a little bit to make it more realistic, and I will also have to adjust a few ideas and habits. I don't think this is something I can keep up long term, but I think I'll do it again for October. I do like how using cash keeps me honest, and keeping track of every single thing keeps me thinking about what I'm spending. I can Just Say No!
...most of the time. :)
Friday, September 24, 2010
c(R)ash diet
I have a surprise for you. Are you ready for this?
Here it is:
When you don't have a job, you don't have money!
You're shocked, right?!
I'm not, because I did this already, a year and a half ago. I'm so over being poor.
I'm also a little restless and bored.
So I took on a challenge. It's not a unique challenge, and it's not even a cool and hip young-person challenge. Oh, no.
This is a challenge from the Guru of Greenbacks herself, Suze Orman!
Last December, she declared that to get back at rising credit card interest rates and fees, people shouldn't buy on credit anymore and just do cash: a Back to Cash Movement!
This summer she had a guest on the show who took the challenge and tried to only use cash for a month and felt successful in managing her spending. I found this intriguing, and so, knowing that I have a very limited amount of money to spend period, I would give it a try. Especially because the last of the wedding bills came through this month (on credit cards).
[I'm actually very responsible with credit cards. I almost always pay the complete amount. If that's not at all possible, I pay as much as I can (a big chunk, way way more than the minimum). My first year of teaching (classroom supplies, school clothes, rent, books for grad school) required so much money that I was in debt the whole time--somehow I had to keep charging as much as I paid each month off the balance. So it took a little more than a year to finally get rid of that. Early last year I had a huge car repair right after I got fired, and without a real job, it took three or four months to pay it off.]
But I've been really good about not putting things on credit cards (other than wedding stuff), and it's easy to keep those pretty clear. So my motivation with this challenge wasn't fighting debt out of desperation. It wasn't about drowning in credit card interest. (Thank god.) It was more about freaking out that I still have regular bills to pay (cell phone, car insurance, other things), in addition to things like FOOD, and only what was left in my bank account. If nothing goes into it, how long will that last? How smart am I being with what little I have?
I do get reckless when I have a job. I'm not talking dropping hundreds of dollars on useless toys, trinkets, toys. But I won't say no to a reasonable urge: I'll buy a book or two here. I'll buy a few clothes there. I'll have a few drinks out with friends. I'll buy a plane ticket! (For a vacation, not just any old time, obviously! :D) I spend money because I have money. (I also save it, of course. But naturally, saving is the first thing to go when I don't have an income. I can't spare anything for later if there's not much coming in now!)
So, back to the plan. First I reviewed my spending on mint.com and then set up a very spartan monthly budget plan. I decided I would only use cash for everything possible--groceries ($80 regular plus $100 for Costco), restaurants ($30), transportation ($20), and miscellaneous/shopping ($50). So that's a grand total of $260 to last me an entire month.
I have one week left and less than twenty dollars to get me there. There's no way I'm going to make it.
I'll provide a full report once the month is over!
Subscribe to:
Posts (Atom)